The argument
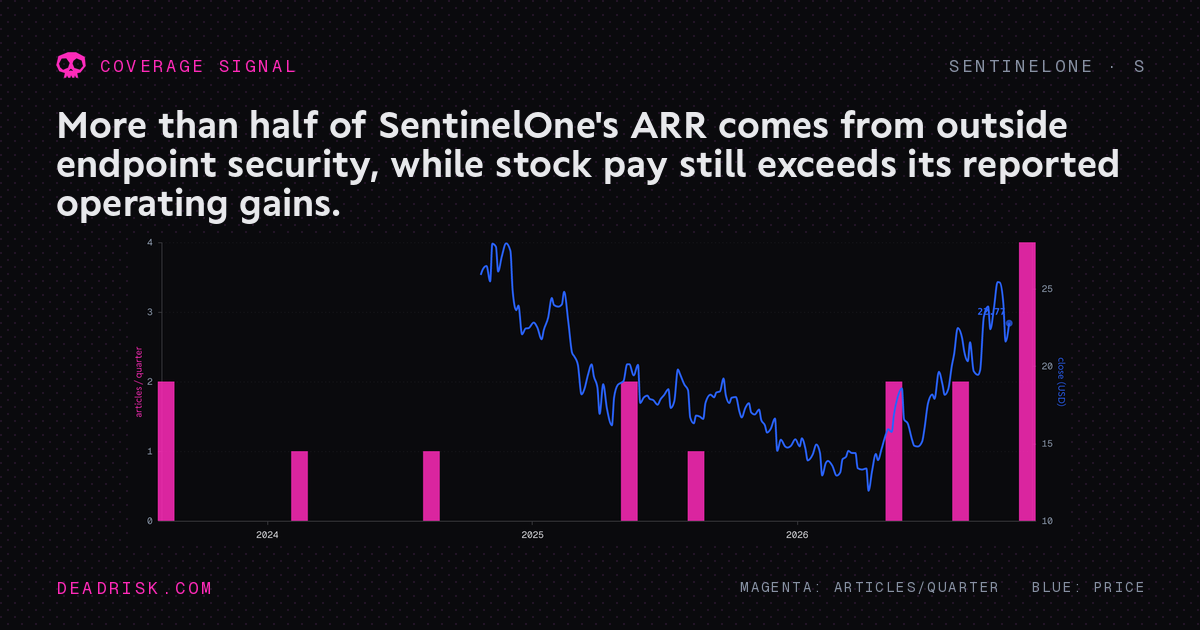
The tape · quarterly coverage amplitude · live quarter blinking
SentinelOne sells software that detects and responds to attacks on computers, cloud workloads and business data. It trades on the NYSE as S. Its August 27 results establish the current scale: $292 million of revenue in the quarter ended July 31, 2026, up 21% from a year earlier, with annual recurring revenue of $1.218 billion, up 22%. Customers spending at least $100,000 in ARR grew 13% to 1,715. Growth in larger accounts is a better test of demand than the number of AI products announced.
The product mix has changed. The filed Q2 presentation puts more than half of ARR outside endpoint security, across data, cloud, AI and other products. That gives SentinelOne several ways to expand within an account. It also makes the old description of a smaller endpoint rival less useful. The question now is whether customers will pay for several tools on one platform at margins that support the business.
The profit figures need care. Q2 non-GAAP operating margin reached 10%, against a GAAP operating loss of 31% of revenue. The July 31 filing records $92.1 million of quarterly stock compensation, including restructuring costs: about 31.5% of sales. Share pay is a large part of the gap between those measures. The broader cyber resilience theme explains the demand case; these costs determine how much of it can reach shareholders.
Cash needs a separate check. The same filing records a remaining Israeli tax-assessment liability of $162.3 million, with 7% annual interest and installments through fiscal 2031. Ordinary second-quarter free cash flow was negative $13.2 million. Over six months, adjusted free cash flow excluded a $30.7 million tax installment. That payment still used cash. The investment balance also includes strategic holdings, which should stay separate from cash and short-term debt securities when assessing liquidity.

The coverage record and the latest results tell different parts of the story. In May 2026, CNBC reported workforce cuts affecting 8% of full-time staff as the company shifted resources toward AI and data. Its revenue outlook fell short of market estimates. That report belongs beside the later results: a new product focus can require lower costs and still leave demand below expectations.
By August, SentinelOne raised its annual outlook to $1.202 billion–$1.207 billion of revenue for fiscal 2027, which ends January 31, 2027. It also expected $124 million–$128 million of non-GAAP operating income. That is evidence of improved execution after May. It does not erase the GAAP loss or establish that the cost changes have finished.
The clearest evidence of new-product demand appears in the Q2 presentation. Combined ARR from Prompt Security and Purple AI nearly tripled from a year earlier. Flex, the purchasing program that lets customers commit across the platform, exceeded 10% of total ARR. These measures show paid adoption and changes in purchasing, beyond a list of releases. The company did not provide the starting dollar base for AI ARR in that presentation. A high growth rate alone cannot show that AI has become a large share of sales.
Acquisitions complicate the comparison. The July 31 10-Q dates the Prompt acquisition to September 5, 2025 and the Observo data-pipeline acquisition to September 22, 2025. Both entered the group after the prior-year Q2 ended. Current growth therefore includes businesses missing from that comparison period. The combined Prompt and Purple number cannot serve as a clean measure of organic AI growth.
Product growth also has to cover its delivery costs. Reported gross margins weakened: GAAP gross margin fell from 75% to 72%, while non-GAAP gross margin fell from 79% to 77%. A larger software platform can improve the value of each customer relationship while becoming more costly to run. Growth in data and AI makes that tension central to the next results.

The spectrogram
Signal decomposition · what the record is made of, by quarter · brightness = share of edges · drift = how far the story moved in meaning
In 2024Q1 the record was 100% acquisition; by 2025Q2 it is 67% regulatory. A price chart shows what a name did; the spectrogram shows what its story is made of.
The brains
Panel not seated
Fewer than the full panel of lenses have read this name. The gauge shows n/3 until it fills.
The machine
The October 22, 2026 TEXXR graph query returned 37 SentinelOne edges across 24 distinct first-seen dates, against 291 total edges for CoreWeave, including one undated, across 103 distinct first-seen dates, queried the same day. Those are extracted relationships and dates, not counts of independent reports. SentinelOne has enough history for a dossier, but a much thinner record than that baseline.
The duplicates matter. Six SentinelOne edges dated May 29–30 describe the workforce cut, weak guidance and market reaction from one CNBC report. Those rows should not become six confirmations of a deteriorating business. Two older acquisition edges likewise describe the same Attivo announcement on successive dates. Counting rows without reading them would overstate both the depth and the range of the record.
The graph also reaches outside product sales. A Reuters report from April 2025 links SentinelOne to the revocation of security clearances. That is a government-access risk, with a separate route into the business from customer adoption. A September 2024 report connects SentinelOne, CrowdStrike and Microsoft through reported macOS compatibility problems. The graph marks that problem as reported rather than settled. Co-occurrence with rivals does not establish which vendor won or lost a customer.
These limits shape the research. The graph tracks changes in products, staffing and government relations. The filings must answer the harder commercial questions: how fast recurring sales grow, whether acquired products expand after integration, and what that growth costs.
The money

Currency: USD. Revenue/net income/capex/FCF cross-checked against filed XBRL.

The record
- The next fiscal 2027 results. Compare ARR growth with Q2’s 22% and revenue growth with 21%. Sustained growth in both would carry more weight than a single product’s rate from an undisclosed base. The Q3 revenue outlook was $309 million–$311 million.
- Product breadth after acquisition anniversaries. Prompt and Observo passed their first purchase anniversaries in September 2026. Future comparable periods can give a clearer view of underlying expansion. Watch for separate AI ARR dollars and the non-endpoint share against Q2’s greater-than-50% baseline.
- Gross margin and compensation together. Use 72% GAAP gross margin and $92.1 million of quarterly stock compensation as the July 2026 baselines. Faster sales paired with falling delivery margin or rising share costs would weaken the operating case.
- The share count in each filing. Guidance assumed 370 million diluted shares in Q3 and 361 million for the full year. These are weighted averages for different periods. Track issued shares and award dilution directly before treating non-GAAP earnings growth as growth per owner.
- Large-account adoption. Compare the next count of customers over $100,000 ARR with 1,715 and its 13% growth rate. A wider platform needs durable expansion within accounts, alongside new customers.
| Quarter | Articles | QoQ | Q-end price | QoQ | The record reads |
|---|---|---|---|---|---|
| 2023Q3 | 2 | — | — | — | first quarter on record |
| 2024Q1 | 1 | -50% | — | — | attention cooled |
| 2024Q3 | 1 | +0% | — | — | attention held |
| 2025Q2 | 2 | +100% | 18.28 USD | — | attention rose |
| 2025Q3 | 1 | -50% | 17.61 USD | -3.7% | attention and price fell together |
| 2026Q2 | 2 | +100% | 16.97 USD | -3.6% | attention rose as price fell |
| 2026Q3 | 2 | +0% | 23.76 USD | +40.0% | price rose, attention steady |
| 2026Q4 open | 4 | +100% | 22.77 USD | -4.2% | attention rose as price fell (quarter in progress) |
Sources
- SentinelOne Q2 fiscal 2027 results — company release, 2026-08-27. Financial results.
- SentinelOne Q2 fiscal 2027 earnings presentation — filed with the SEC, 2026-08-27. Product and ARR measures.
- SentinelOne Form 10-Q, quarter ended July 31, 2026 — filed 2026-08-28. Costs, shares and acquisitions.
- SentinelOne workforce cuts and revenue guidance — CNBC, 2026-05-29. Original report; TEXXR records 1169882 and 1169900.
- Cybersecurity industry response to clearance action — Reuters, published 2025-04-10; TEXXR record dated 2025-04-11. Original report; TEXXR record.
- macOS Sequoia security-tool compatibility reports — TechCrunch, 2024-09-19; TEXXR record dated 2024-09-20. Original report; TEXXR record.
- Corpus method: full entity-edge queries for SentinelOne and CoreWeave, 2026-10-22. Returned counts were 37/24 and 291/103 edges/distinct dated first-seen dates, with one undated CoreWeave edge. Repeated dates and summaries describe extraction structure, not independent evidence.