The argument
The tape · quarterly coverage amplitude · live quarter blinking
Tenable helps customers find weaknesses across their systems and decide which to fix first. It trades on Nasdaq as TENB. Its Q2 2026 results, released July 29, put quarterly revenue at $268.5 million, up 8.6% from a year earlier. Recurring revenue supplied 95% of the total. This is an established subscription business trying to sell a broader set of tools to customers who already pay it.
The wider platform is gaining a larger share of new work. Tenable One accounted for 50% of new sales in Q2. That figure describes the mix of new sales, not half of all company revenue. It is useful evidence that customers are adopting the platform. It cannot show, by itself, whether total demand is accelerating.
The backlog gives a second check. Remaining performance obligations, the revenue still due under contracted work, rose 15.4% to $1.026 billion at June 30. The short-term portion rose 12.3% to $721.1 million. Both grew faster than quarterly sales. The central question is whether that gap turns into faster reported revenue, without a rise in discounts or selling costs. Tenable adds an exposure-management view to the broader cyber resilience theme: finding and reducing weaknesses before recovery becomes necessary.

The older acquisition record explains the product direction. Tenable announced the Alsid agreement in February 2021 to add Active Directory security. In September 2021, it announced the Accurics agreement, extending its cloud tools into risks in infrastructure code before deployment. These were distinct problems, tied to identity and cloud configuration. Combining them creates the chance to rank related weaknesses within one customer environment.
The coverage record also shows Tenable as a researcher and critic of larger platforms. In August 2023, CyberScoop covered its criticism of Microsoft’s handling of an Azure flaw. The Record then reported that Microsoft had fixed the problem. Those reports establish a role in vulnerability research. They do not show that a customer bought more software as a result. Technical attention and commercial progress need separate evidence.
Leadership changed after Amit Yoran’s death in January 2025. The company appointed Steve Vintz and Mark Thurmond as permanent co-CEOs in April, dividing product and administrative work from sales and customer functions. The current platform push therefore needs to be read alongside an operating transition, not treated as the continuation of one unchanged management plan.
The strongest recent product milestone is a shipped release. Hexa AI became generally available on May 20, 2026 for Tenable One Foundation and Advanced customers. It supports reasoning across exposures, custom agents and workflows through the Model Context Protocol. Its remediation features can create and route work, generate policies and produce reports. Those tasks give the release a concrete use. The announcement does not establish how much extra customers pay for Hexa or how much work they complete with it.
Commercial results remain the stricter test. In Q2, Tenable added 381 enterprise platform customers and 32 net new six-figure customers. It raised annual revenue guidance to $1.075 billion–$1.081 billion. Yet its Q3 forecast remained $270 million–$273 million. Wider platform adoption has begun to change the mix; company growth still needs to show the benefit.

The spectrogram
Signal decomposition · what the record is made of, by quarter · brightness = share of edges · drift = how far the story moved in meaning
The brains
Panel not seated
Fewer than the full panel of lenses have read this name. The gauge shows n/3 until it fills.
The machine
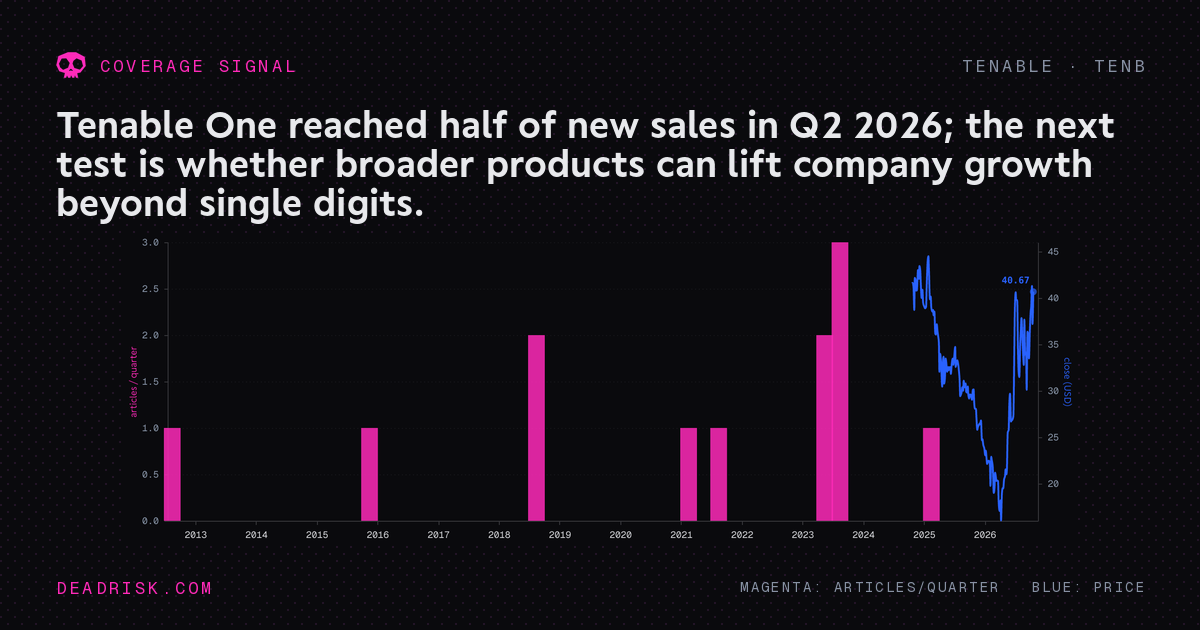
The October 22, 2026 TEXXR query returned 11 Tenable edges across eight distinct first-seen dates. The same-day CoreWeave query returned 291 total edges, including one undated, across 103 distinct first-seen dates. Tenable’s record is sparse by that baseline. Several entries describe acquisitions and vulnerability disputes, rather than a continuous earnings history.
Even that small count needs inspection. Two Tenable edges, dated August 5 and 6, 2023, cover the Microsoft dispute and link to the same original report. They are not two independent confirmations. Three further edges share the July 4, 2018 IPO-filing date. The graph records several facts from a news event; its row count cannot measure the number of times the business changed.
Text search brings another problem. Cached hits include stories using “tenable” as an ordinary adjective in reports about other companies. They do not belong in the company history. The graph’s Alsid and Accurics relationships are relevant; an unrelated sentence about whether a policy is tenable is not. That distinction keeps a thin coverage record from looking broader than it is.
The practical result is a limited historical claim. The corpus supports Tenable’s expansion across identity and cloud risk and its place in security research. The latest revenue, backlog, customer and product-adoption figures come from linked company filings. Neither source should borrow the authority of the other.
The money

Currency: USD. Revenue/net income/capex/FCF cross-checked against filed XBRL.

The record
- Q3 2026 revenue and backlog. Measure results against the July 29 outlook of $270 million–$273 million. Compare short-term RPO growth with 12.3% and total RPO growth with 15.4%. A longer contract term can raise total backlog without the same near-term revenue effect.
- Platform mix and total growth together. The 50% Tenable One share of new sales is the Q2 baseline. A rising share matters more if overall new business and revenue also grow faster. Watch for dollar figures that distinguish a larger business from a changed mix.
- Cash after financing costs. Annual guidance reconciles unlevered cash flow of $289 million–$295 million to free cash flow of $265 million–$271 million. The $24 million difference is financing cash costs. Track the latter measure; it does not deduct repayment of debt principal.
- Compensation alongside operating profit. The June 30 filing reports Q2 stock compensation of $46.3 million, about 17.3% of revenue, against $12.4 million of GAAP operating income. Non-GAAP operating margin reached 24.7%; the gap remains material.
- Use of Hexa after launch. Future customer counts, paid adoption or measured remediation use would strengthen the May availability announcement. Membership in AI partner programs does not supply those missing measures.
- Debt and share count. The June filing shows $358.1 million of term-loan principal and $298.2 million of cash and short-term investments, including $8.9 million of restricted cash. Repurchases used $230.2 million in the first half. Follow cash, debt and issued shares together to judge whether cash generation improves the balance sheet as well as reducing shares.
| Quarter | Articles | QoQ | Q-end price | QoQ | The record reads |
|---|---|---|---|---|---|
| 2012Q3 | 1 | — | — | — | first quarter on record |
| 2015Q4 | 1 | +0% | — | — | attention held |
| 2018Q3 | 2 | +100% | — | — | attention rose |
| 2021Q1 | 1 | -50% | — | — | attention cooled |
| 2021Q3 | 1 | +0% | — | — | attention held |
| 2023Q2 | 2 | +100% | — | — | attention rose |
| 2023Q3 | 3 | +50% | — | — | attention rose |
| 2025Q1 | 1 | -67% | 34.98 USD | — | attention cooled |
Sources
- Tenable Q2 2026 results — company release filed with the SEC, 2026-07-29. Revenue and cash reconciliation.
- Tenable Form 10-Q, quarter ended June 30, 2026. Debt, compensation and repurchases.
- Tenable Q2 2026 investor presentation, 2026-07-29. Platform sales mix.
- Tenable Hexa AI general availability — company release, 2026-05-20. Shipped capabilities.
- Alsid acquisition agreement — Tenable, 2021-02-10. Identity security expansion. TEXXR edge 306057 first seen 2021-02-11.
- Accurics acquisition agreement — Tenable, 2021-09-13. Cloud security expansion. TEXXR edge 297820 first seen 2021-09-14.
- Tenable criticism of Microsoft’s Azure response — CyberScoop, TEXXR record dated 2023-08-03. Original report; TEXXR record.
- Microsoft fixes Azure flaw after criticism — The Record; TEXXR records dated 2023-08-05 and 2023-08-06. Original report; records 842815 and 842849.
- Amit Yoran dies — TechCrunch, 2025-01-04; TEXXR record dated 2025-01-05. Original report; TEXXR record.
- Permanent co-CEO appointments — Tenable, 2025-04-16. Company announcement.
- Corpus method: full entity-edge queries for Tenable and CoreWeave, 2026-10-22, returned 11/8 and 291/103 edges/distinct dated first-seen dates, with one undated CoreWeave edge. These counts describe the extracted record, not independent reports.